Tree Fell on Your Roof? What NJ Homeowners Should Do First
A tree or large limb on your roof is scary. Here's what NJ homeowners should do first, how insurance usually handles it, and what repairs typically cost.
ARAmerican Roofing Pros··6 min read
If a tree or large limb falls on your roof, get everyone out of the affected rooms, stay away from downed wires, and call 911 or your utility if lines are involved. Once everyone is safe, document the damage, call your insurance company, and have a roofer get the opening covered so rain doesn't turn a roof problem into a ceiling, insulation and drywall problem. Don't try to climb up or cut the tree off yourself.
Late fall and winter are prime time for this in New Jersey. Nor'easters bring strong gusts, saturated ground loosens roots, and heavy wet snow or ice adds weight to limbs. Here's how to handle it step by step, what insurance usually covers, and what repairs tend to cost.
Step 1: Make Sure Everyone Is Safe
A tree on a roof can put far more weight on the framing than it was built to carry, and that load can shift as wind continues or as the tree settles. Treat the situation as unstable until a professional says otherwise.
- Leave any room where the ceiling is cracked, bowing or dripping, and keep kids and pets out.
- Stay at least 30 feet from any downed or sagging power line. Assume it's live and report it to your utility, such as PSE&G, JCP&L or Atlantic City Electric.
- If you smell gas, leave the house and call your gas utility or 911 from outside.
- If water is reaching light fixtures or outlets, turn off power to that area at the breaker panel if you can do it safely.
- Do not climb onto the roof or start cutting branches. Tension in a fallen trunk can cause it to roll or spring unexpectedly.
Step 2: Document Everything Before Anything Moves
Your insurance claim will go much smoother with clear evidence. Take photos and video before the tree is removed, because once it's gone, the adjuster can only see the aftermath.
- Wide shots of the house showing where the tree landed, from several angles.
- Close-ups of broken shingles, crushed gutters, damaged siding and any visible holes.
- Interior photos of ceiling stains, cracks, wet insulation and damaged belongings.
- A shot of the tree's base or stump, which shows whether it was healthy or rotted.
Write down the date and time and keep every receipt for emergency expenses, including tarping, tree removal, water cleanup and hotel stays if the house isn't livable.
Step 3: Call Your Insurer and Get the Roof Covered
Report the claim as soon as possible. Most homeowners policies require you to take reasonable steps to prevent further damage, so getting the roof temporarily protected is part of your responsibility, and the cost is typically reimbursable.
In practice, the tree usually has to come off before the roof can be properly tarped. That often means a tree service with a crane or bucket truck working alongside a roofer. A good roofing contractor can coordinate the timing so the roof is covered the same day the tree is lifted off. Our storm and roof damage repair team handles emergency tarping and can work with your tree company to keep the gap as short as possible.
Does insurance cover a tree falling on your roof?
In most New Jersey homeowners policies, damage to your house from a tree knocked down by wind, lightning, ice or snow is covered, minus your deductible. A few points tend to come up:
- Neighbor's tree: If a healthy neighbor's tree falls on your house in a storm, you generally file with your own insurer. If the tree was obviously dead or diseased and your neighbor was warned, liability may shift to them.
- Dead or neglected trees: If the tree on your property was visibly rotted, an insurer may argue the damage resulted from poor maintenance rather than a storm.
- Tree removal limits: Many policies cover removing the part of the tree that's on the house, but often cap tree removal at a modest amount, commonly in the $500 to $1,000 range. Check your declarations page.
- Trees that miss the house: A tree that falls in the yard without hitting a structure usually isn't covered for removal.
For a deeper walk-through of the claims process, see our post on storm damage roof insurance claim tips for New Jersey.
What Damage to Look For Once the Tree Is Off
Some tree damage is obvious, like a hole through the roof. But even a limb that seemed to just glance off can cause problems that show up weeks later as a leak. A thorough inspection should check both the outside and the attic.
- Cracked, punctured or missing shingles, and shingles that were scuffed loose from their seal strips.
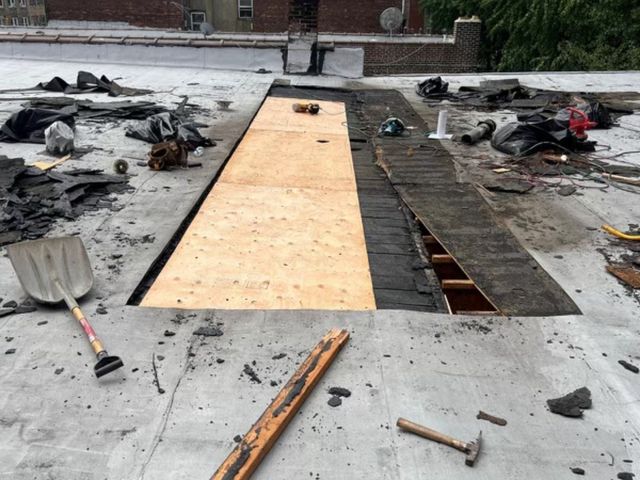
- Cracked or broken roof decking (the plywood or boards under the shingles).
- Cracked, split or bowed rafters or trusses, visible from the attic.
- Sagging along the roofline or ridge when viewed from the street.
- Bent drip edge, crushed gutters, and pulled-away fascia boards.
- Damaged flashing around chimneys, vents and skylights.
- New drywall cracks, nail pops or doors that suddenly stick inside the house, which can signal a structural shift.
If shingles were stripped by wind but the tree itself didn't punch through, our guide on what to do when shingles blow off covers that scenario in more detail.
Repair or Replace? What It Typically Costs
Costs vary widely depending on how big the tree was, where it hit, your roof's pitch and material, and the condition of the roof before the storm. These ranges are general and only an on-site inspection can give you a real number.
- Emergency tarping: often a few hundred dollars up to $1,500 or more for large or steep roofs.
- Tree removal from a house: commonly $1,000 to $5,000+, more when a crane is needed or access is tight.
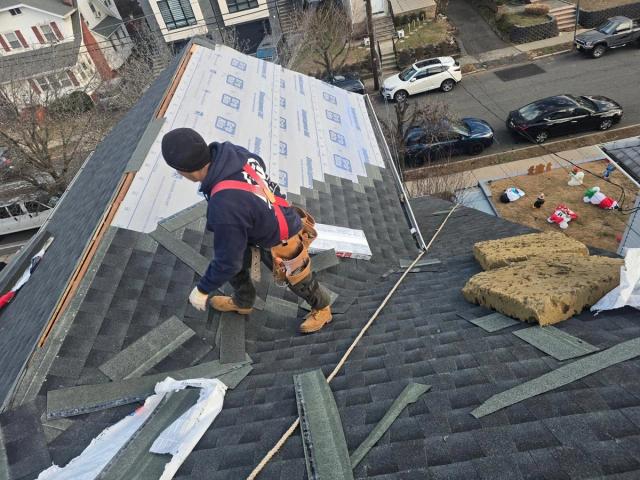
- Localized roof repair (shingles, underlayment and a section of decking): roughly $800 to $3,500.
- Structural framing repair (rafters, trusses, ridge): often $3,000 to $15,000+, depending on how much framing is involved.
If your roof was already near the end of its life, a section repair may not make sense. Matching discontinued or weathered shingles can be difficult, and patching a 20-year-old roof leaves you paying twice when the rest fails. In some cases the insurance payout for the damaged area can go toward a full roof replacement, with you covering the difference. Structural repairs and reroofing in New Jersey generally require a permit from your local building department, which a licensed contractor should handle.
How to Lower the Risk This Winter
November is actually a good time to look at the trees around your house. With the leaves down, dead limbs and weak branch unions are much easier to spot.
- Keep branches trimmed back at least 6 to 10 feet from the roof.
- Watch for trees that lean toward the house, have mushrooms or fungus at the base, or show cracks in the trunk.
- Have a certified arborist evaluate large trees close to the house, especially mature oaks and maples common in North and Central Jersey.
- If a neighbor's tree looks dangerous, put your concern in writing. It can matter later if it falls.
- Clear gutters after leaf drop so storm runoff doesn't back up under shingles that branches may have loosened.
Next Steps
If a tree or limb has hit your roof, safety comes first, then photos, then a call to your insurer and a roofer. As a GAF Master Elite® contractor with 20 years of experience across New Jersey, American Roofing Pros can tarp the damage, inspect the decking and framing, and give you a written, itemized estimate with photos you can share with your adjuster.
Call us at (877) 228-1042 or request a free estimate and we'll help you get your roof, and your home, back to normal.